
How Much Money Can You Save by Downsizing Your Bay Area Home?
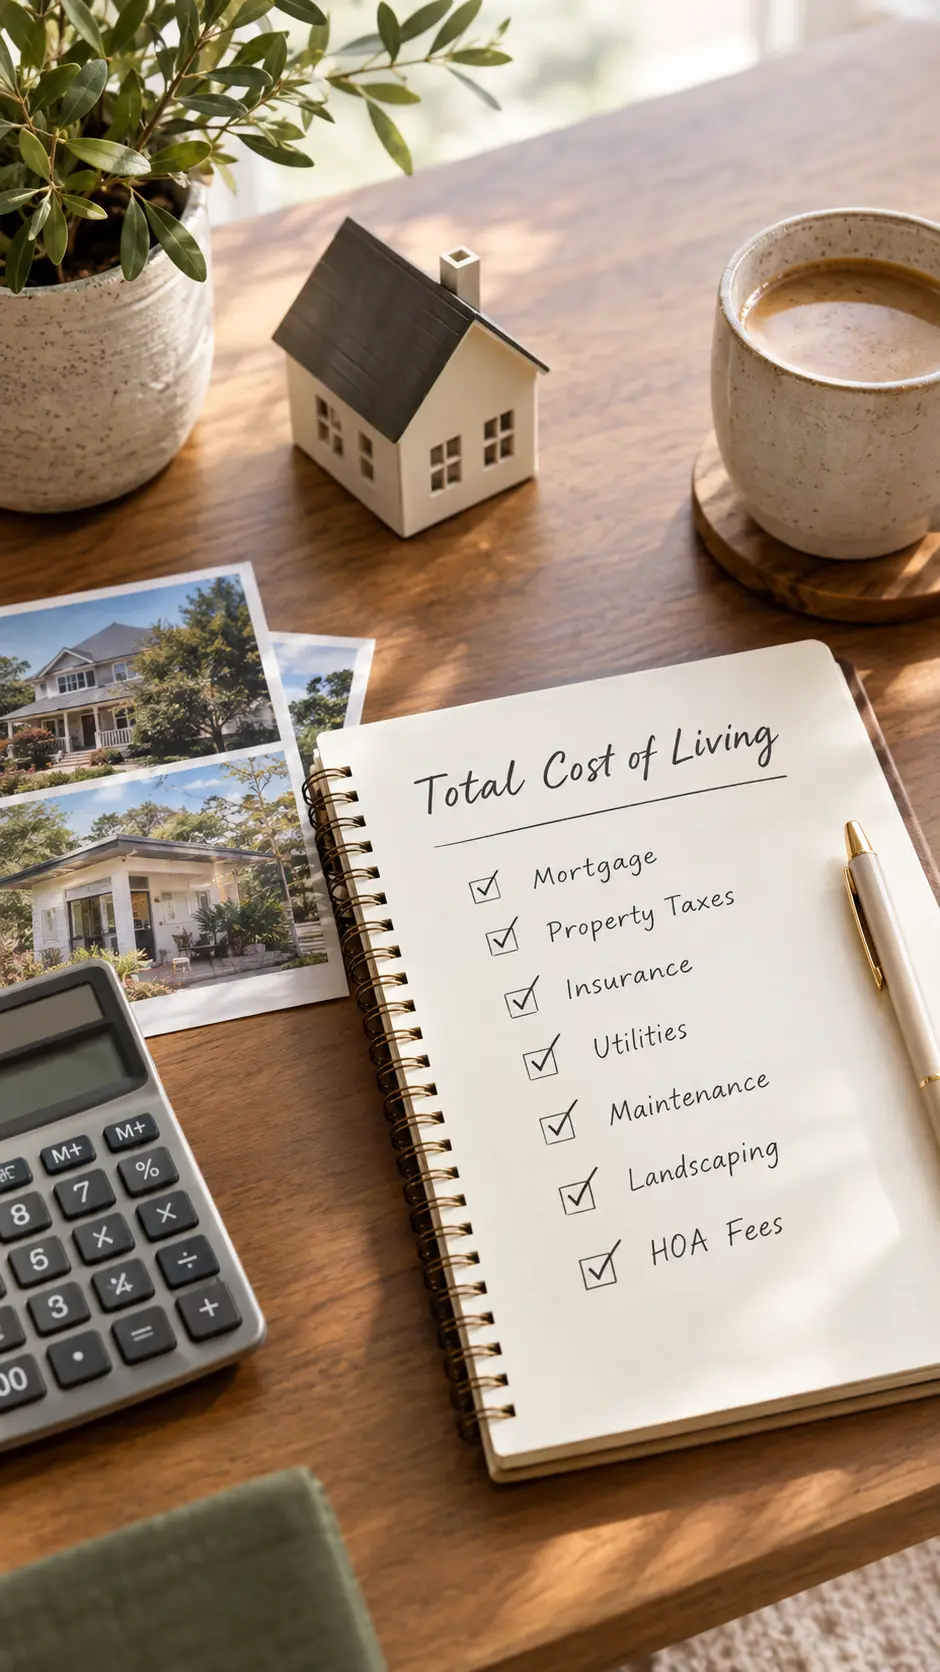
For many Bay Area homeowners, downsizing is about more than moving into a smaller home.
It can also be a financial decision.
If you've lived in your home for many years, you may have built substantial equity while your property has become more expensive to maintain. Moving into a smaller property could potentially reduce some housing expenses while giving you access to equity you've accumulated.
But how much money can you actually save by downsizing your Bay Area home?
The answer depends on your current home, the property you purchase, your mortgage, property taxes, HOA costs, maintenance, insurance, and how much equity you have.
In some cases, downsizing can significantly improve monthly cash flow. In others, the savings may be smaller than expected—particularly if you purchase a smaller home in a highly desirable Bay Area neighborhood.
The key is to compare the entire financial picture, not just the difference in purchase price.
What Does Downsizing Actually Save You?
When people think about downsizing, they often focus on the mortgage.
But your housing costs extend well beyond your monthly loan payment.
Potential savings can come from:
- Mortgage payments
- Property taxes
- Homeowners insurance
- Utilities
- Landscaping
- Repairs
- Maintenance
- HOA costs
- Furnishing and upkeep
At the same time, some of these expenses may increase after downsizing.
For example, a condominium may have lower maintenance responsibilities but higher HOA dues.
That's why you need to calculate your current and future costs side by side.
Start With Your Current Monthly Housing Costs
Before determining how much you could save, calculate what your current home costs you each month.
Include:
Mortgage
Look at your current principal and interest payment.
Also consider your remaining mortgage balance and interest rate.
Property Taxes
Property taxes can represent a significant ongoing expense in the Bay Area.
Insurance
Include your homeowners insurance and any other property-related insurance costs.
Utilities
Compare:
- Electricity
- Gas
- Water
- Trash
- Other recurring services
A smaller home may use less energy, but the actual savings will depend on the properties.
Maintenance
Estimate your average annual spending on:
- Plumbing
- Electrical work
- Appliances
- Roof maintenance
- Landscaping
- Painting
- Exterior repairs
Some maintenance expenses are irregular, so look at several years of history rather than one unusually low year.
Landscaping
A large yard can require ongoing:
- Gardening
- Irrigation
- Tree maintenance
- Lawn care
- Landscaping repairs
Moving to a condominium or smaller property may substantially reduce these responsibilities.
Then Calculate the Cost of the Smaller Home
Once you've identified your current expenses, estimate the same categories for your next property.
For example:
Current Home
Mortgage + taxes + insurance + utilities + maintenance + landscaping
versus
Smaller Home
Mortgage + taxes + insurance + utilities + HOA + maintenance
The difference gives you a much more realistic estimate of potential monthly savings.
Example: How Downsizing Could Change Your Monthly Costs
Imagine a homeowner currently spends approximately:
- $4,000 mortgage
- $1,500 property taxes
- $250 insurance
- $400 utilities
- $500 average maintenance
- $300 landscaping
That's approximately $6,950 per month in housing-related expenses.
Now suppose they move into a smaller property and their estimated expenses become:
- $2,500 mortgage
- $1,100 property taxes
- $150 insurance
- $250 utilities
- $200 maintenance
- $600 HOA
That's approximately $4,800 per month.
The potential difference would be around $2,150 per month, or approximately $25,800 per year.
This is only an illustration—not a prediction of what any particular homeowner will save.
Your actual numbers could be very different.
Your Mortgage Can Make a Major Difference
Mortgage costs may be one of the biggest factors in determining whether downsizing creates meaningful savings.
If you sell a home with significant equity and purchase a substantially less expensive property, you may be able to reduce the amount you need to finance.
In some cases, homeowners may be able to purchase the next property with a much smaller mortgage—or potentially without one.
That can dramatically change monthly cash flow.
However, current mortgage rates, financing terms, and the price of your next home all matter.
Your Home Equity Is a Major Part of the Equation
For longtime Bay Area homeowners, equity may be one of the biggest financial benefits of downsizing.
Consider a simplified example:
Your home sells for:
$1,500,000
You owe:
$400,000
That leaves approximately:
$1,100,000 in gross equity
before selling costs and other adjustments.
If you purchase a smaller home for $900,000, you may be able to use some of your proceeds toward the new property and potentially retain a portion of the remaining equity.
But the actual amount you walk away with depends on the complete transaction.
Don't Forget Selling Costs
The amount you save by downsizing isn't simply:
Current home value − new home price
You need to account for the costs of selling and buying.
These can include:
- Real estate commissions
- Transfer taxes
- Repairs
- Staging
- Moving
- Closing costs
- Inspections
- Loan costs
- Other transaction expenses
These costs can reduce the amount of equity available after the move.
Consider the Break-Even Period
This is an important question:
How long will it take for my monthly savings to offset the costs of downsizing?
Suppose your move costs $60,000 in combined selling, buying, moving, and preparation expenses.
If your new housing costs are $2,000 lower per month:
$60,000 ÷ $2,000 = 30 months
Your approximate break-even period would be 30 months.
This is a simplified example, but it demonstrates why transaction costs matter.
If you expect to remain in the smaller home for many years, the long-term savings may be more meaningful.
Property Taxes Require Special Attention
Downsizing doesn't necessarily mean your property tax bill will decrease by the amount you expect.
California property tax rules can be complex, and the treatment of a new purchase depends on your circumstances.
Certain homeowners may qualify for provisions that affect how property taxes are handled when purchasing a replacement property.
Because eligibility and tax consequences can vary, discuss your situation with the appropriate county assessor and a qualified tax professional before making a decision based on projected property taxes.
HOA Fees Can Reduce Your Savings
Many downsizers consider condominiums or townhomes because they require less exterior maintenance.
But HOA dues can be substantial.
For example, you might save money on:
- Landscaping
- Exterior maintenance
- Certain repairs
while taking on:
- Monthly HOA dues
- Special assessments
- Shared maintenance costs
Before buying, review the HOA's financial health, reserves, rules, insurance, and recent or planned assessments.
A lower-maintenance property isn't necessarily a lower-cost property.
Smaller Doesn't Always Mean Cheaper
This is particularly important in the Bay Area.
A smaller property in a highly desirable location may cost more than a much larger home elsewhere.
You could downsize from 2,500 square feet to 1,300 square feet and still pay a substantial amount for:
- Location
- Walkability
- Transportation
- Neighborhood amenities
- School access
- Limited inventory
You need to determine whether you're downsizing both your home and your overall housing costs or simply downsizing your square footage.
You May Be Paying More for Location
Some homeowners intentionally trade space for convenience.
For example, you might move from a large home with a yard into a smaller condominium near:
- BART
- Restaurants
- Grocery stores
- Parks
- Family
- Healthcare
Your housing costs might not fall dramatically.
But your transportation expenses, maintenance responsibilities, and time spent driving may decrease.
That can still represent a meaningful lifestyle improvement.
Don't Underestimate Maintenance Savings
Maintenance can be difficult to calculate because major expenses aren't predictable.
A large home might require:
- Roof replacement
- Exterior painting
- Tree work
- Landscaping
- HVAC replacement
- Plumbing repairs
A smaller or newer property may reduce some of these expenses.
If an HOA covers certain exterior responsibilities, that may further reduce your personal maintenance burden.
Look at maintenance over a five- to ten-year period, not just your current year's expenses.
Your Utility Savings May Be Smaller Than Expected
A smaller home generally requires less energy to heat and cool.
But utility savings depend on:
- Construction
- Insulation
- HVAC efficiency
- Climate
- Number of occupants
- Energy usage
Don't make major financial decisions based on assumed utility savings.
Use your actual historical bills whenever possible.
What About Insurance?
Insurance costs can change when you move.
A smaller property may have a lower insurance premium, but condominium owners also need to understand what the HOA's master policy covers versus what they are personally responsible for.
Review the insurance requirements before purchasing.
Downsizing Can Also Free Up Your Time
Not every benefit appears on a financial statement.
Consider how much time you currently spend maintaining your home.
If you reduce:
- Yard work
- Cleaning
- Repairs
- Organization
- Home projects
you may gain significant personal time.
For some homeowners, that is one of the biggest benefits of downsizing.
What Could You Do With the Money You Save?
If downsizing reduces your monthly expenses, you may be able to redirect the difference toward other priorities.
For example:
- Retirement savings
- Investments
- Travel
- Family
- Hobbies
- Emergency reserves
- Debt reduction
The financial benefit becomes more meaningful when you have a plan for the money you free up.
What If You Don't Need a Mortgage?
Some homeowners with substantial equity may consider purchasing their next home with cash.
This can potentially eliminate:
- Monthly principal payments
- Interest expense
- Certain loan-related costs
However, using all of your available cash for a home isn't necessarily the best financial strategy.
You should consider liquidity, investment opportunities, taxes, and your broader financial plan before making a cash purchase.
Could Downsizing Increase Your Housing Costs?
Yes.
This is one of the most important things to understand.
Your new home could have:
- Higher HOA dues
- Higher property taxes than expected
- Higher insurance
- Significant special assessments
- Expensive maintenance
- A higher purchase price than anticipated
You may also choose to move into a more expensive neighborhood.
Therefore, downsizing should never be evaluated solely on square footage.
How Much Equity Could You Potentially Unlock?
This is one of the most common questions homeowners have.
The calculation starts with:
Estimated sale price
minus:
Mortgage payoff
minus:
Selling expenses
= Estimated net proceeds
Then compare that amount with:
Purchase price of your next home + buying costs
The difference can give you an initial estimate of how much capital you may retain after the move.
A detailed analysis should also account for taxes and your specific financial circumstances.
Consider the Opportunity Cost of Your Equity
Suppose downsizing allows you to free up $400,000.
That money could potentially:
- Remain in cash
- Be invested
- Reduce debt
- Support retirement
- Fund other goals
The question becomes:
What is the best use of that $400,000?
This is why downsizing can be both a real estate decision and a broader financial planning decision.
Is Downsizing Worth It If You Only Save $500 a Month?
Potentially.
Monthly savings aren't the only consideration.
You may also gain:
- Less maintenance
- More convenient location
- More manageable space
- Less responsibility
- More accessible layout
- Greater liquidity
If the smaller home better matches your lifestyle, the move may still make sense.
Is Downsizing Worth It If You Save $2,000 a Month?
It may be even more compelling financially.
A $2,000 monthly reduction represents:
$24,000 per year
Over five years, that's:
$120,000
before considering changes in expenses, investment returns, taxes, or other factors.
Again, the actual savings depend on your circumstances.
Consider the Cost of Waiting
There's another side to the calculation.
What happens if you stay in your current home for another five years?
You may continue paying for:
- Larger utility bills
- Landscaping
- Maintenance
- Repairs
- Unused space
You may also delay accessing the equity in your home.
On the other hand, moving also has costs.
The goal is to compare both scenarios rather than assuming that downsizing is automatically better.
A Simple Downsizing Savings Worksheet
Before making a decision, compare your current and projected expenses.
|
Expense |
Current Home |
Smaller Home |
Potential Difference |
|
Mortgage |
$ |
$ |
$ |
|
Property Taxes |
$ |
$ |
$ |
|
Insurance |
$ |
$ |
$ |
|
Utilities |
$ |
$ |
$ |
|
Maintenance |
$ |
$ |
$ |
|
Landscaping |
$ |
$ |
$ |
|
HOA |
$ |
$ |
$ |
|
Total Monthly Cost |
$ |
$ |
$ |
|
Annual Cost |
$ |
$ |
$ |
Then separately calculate your estimated net equity after selling and purchasing the replacement property.
When Downsizing May Make Financial Sense
Downsizing may be worth considering if:
- You have substantial home equity.
- Your current home is larger than you need.
- Maintenance costs are significant.
- You want lower monthly expenses.
- You can purchase a smaller home at a substantially lower cost.
- You want to access some of your equity.
- You're willing to trade space for convenience.
- You plan to stay in the new home for several years.
When Downsizing May Not Save Much
The financial benefit may be limited if:
- Your next home costs nearly as much.
- HOA dues are high.
- Selling and buying costs are substantial.
- You move into a more expensive neighborhood.
- Your new property needs significant repairs.
- Your current mortgage is unusually favorable.
- You still need substantial space.
In those cases, downsizing may still provide lifestyle benefits, but the financial savings may be modest.
The Bay Area Perspective
For Bay Area homeowners, downsizing requires a particularly careful look at value versus cost.
Your home's value is determined by more than its size.
Location, neighborhood demand, condition, property type, amenities, and current market conditions all influence what buyers may be willing to pay.
Your next home is subject to those same forces.
This is where an accurate valuation becomes important.
You need to know not only what your current home might sell for, but also whether the smaller property you're considering represents good value.
Why an Appraiser's Perspective Can Help
A real estate agent can help you understand market activity, comparable sales, buyer demand, and pricing strategy.
An appraisal background adds another layer of valuation analysis.
By looking carefully at comparable properties and property-specific characteristics, you can make a more informed decision about:
- Current market value
- Potential sale price
- Replacement property value
- Price per square foot
- Neighborhood differences
- Long-term value considerations
The goal isn't simply to sell one home and buy another.
It's to make sure the overall move makes sense.
The Bottom Line
How much money can you save by downsizing your Bay Area home?
There isn't a single number.
Your savings could come from:
Lower mortgage costs
Lower maintenance
Lower utilities
Reduced landscaping
Potentially lower insurance
Less space to maintain
And potentially from unlocking home equity.
But those savings need to be weighed against:
Selling costs
Buying costs
HOA fees
Property taxes
The price of your next home
Moving expenses
Potential repairs
The most useful calculation is not simply:
"How much smaller will my home be?"
It's:
"How will my total cost of housing, available equity, and lifestyle change after I move?"
That's the number that can help you determine whether downsizing is truly worth it.
About Parisa Samimi
With 25 years of experience in residential and investment real estate, Parisa is recognized as a leading top producer across the San Francisco Bay Area. Her background as a real estate appraiser gives her a rare valuation advantage, allowing clients to make informed, strategic decisions in every market condition.
Parisa's work is defined by precision, integrity, and an unwavering attention to detail. She brings a hands-on, solutions-driven approach to every transaction, ensuring that both buyers and sellers feel guided, protected, and empowered throughout the process.
Her passion for the business is evident in the energy and care she brings to each client relationship, qualities that consistently set her apart. Actively representing both buyers and sellers, Parisa is known for her deep market knowledge, strong negotiation skills, and commitment to achieving exceptional results.
Whether preparing a home for the market, navigating complex investment opportunities, or helping clients find the perfect property, she delivers a thoughtful and elevated experience at every step.
Want to Know How Much You Could Save by Downsizing?
Before making a move, you need more than an estimate of your home's value.
You need to understand what you could potentially net from a sale, what your next home may cost, and how your monthly expenses could change.
Contact Parisa Samimi for a personalized Bay Area downsizing consultation.
With 25 years of experience and a background as a real estate appraiser, Parisa can help you evaluate your home's value, compare potential replacement properties, and develop a strategy based on both the numbers and the lifestyle you want.
Don't guess what downsizing could save you. Calculate it before you make the move.
Categories
Recent Posts


GET MORE INFORMATION
Parisa Samimi
Founder & Real Estate Broker License ID: 01858122
Founder & Real Estate Broker License ID: 01858122